Higher Rates Put Buyers and Sellers Under Pressure
FOX Business reports that the Federal Reserve’s latest interest rate decision is reshaping the housing market for both sides of a transaction. With financing costs rising and fewer purchasers able to qualify, sellers who remain anchored to peak-market pricing may face longer marketing periods and mounting pressure to adjust.
Joe DaGrosa, founder and chairman of DaGrosa Capital Partners, told the outlet that expectations often take time to reset. Buyers, he said, may wait for a more favorable mortgage environment, while sellers contend with a smaller pool of qualified prospects. Brett Rubin, vice president of the Bowers Group at Compass, described the same imbalance in practical terms: fewer buyers mean fewer opportunities to sell, less competition and more listings sitting on the market.
Who Joe DaGrosa Is
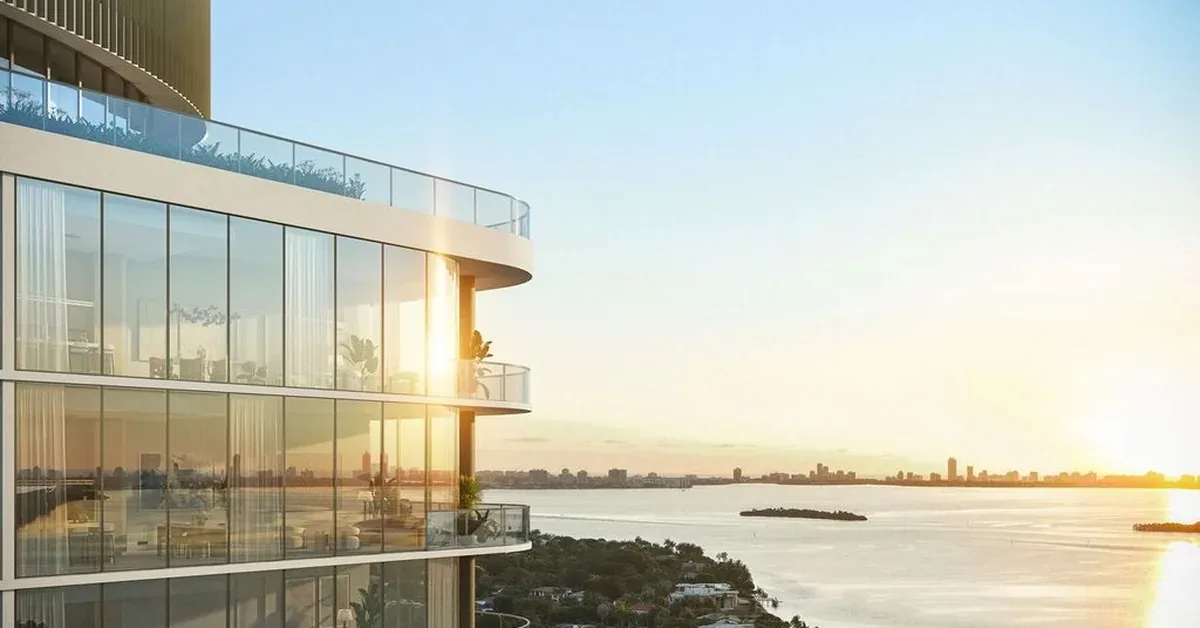
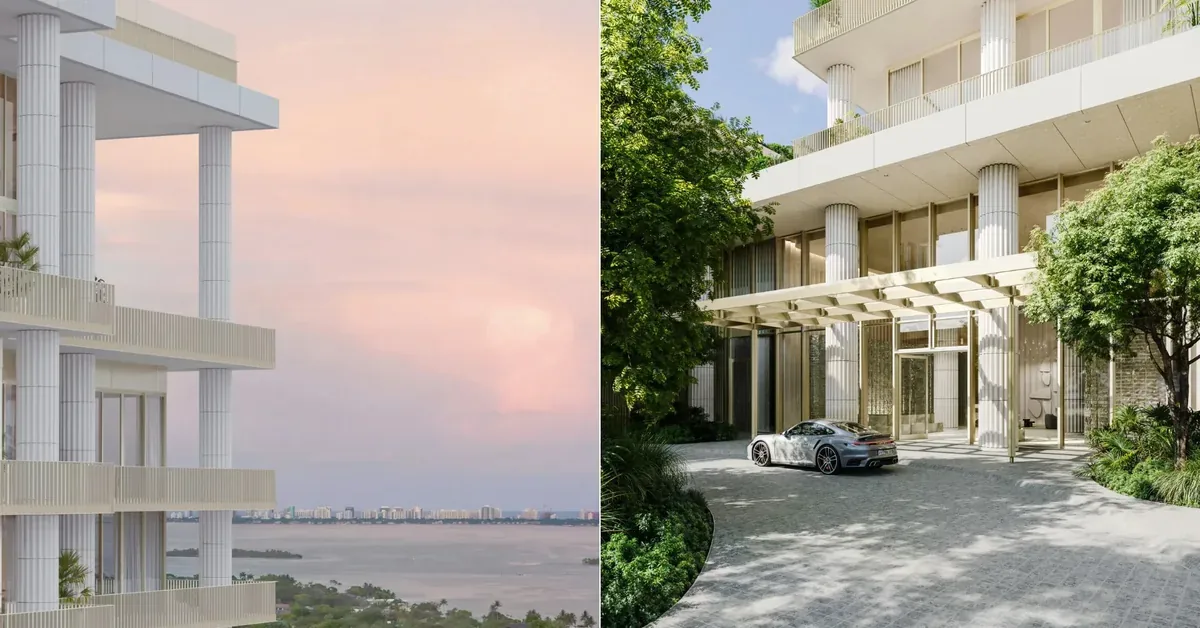
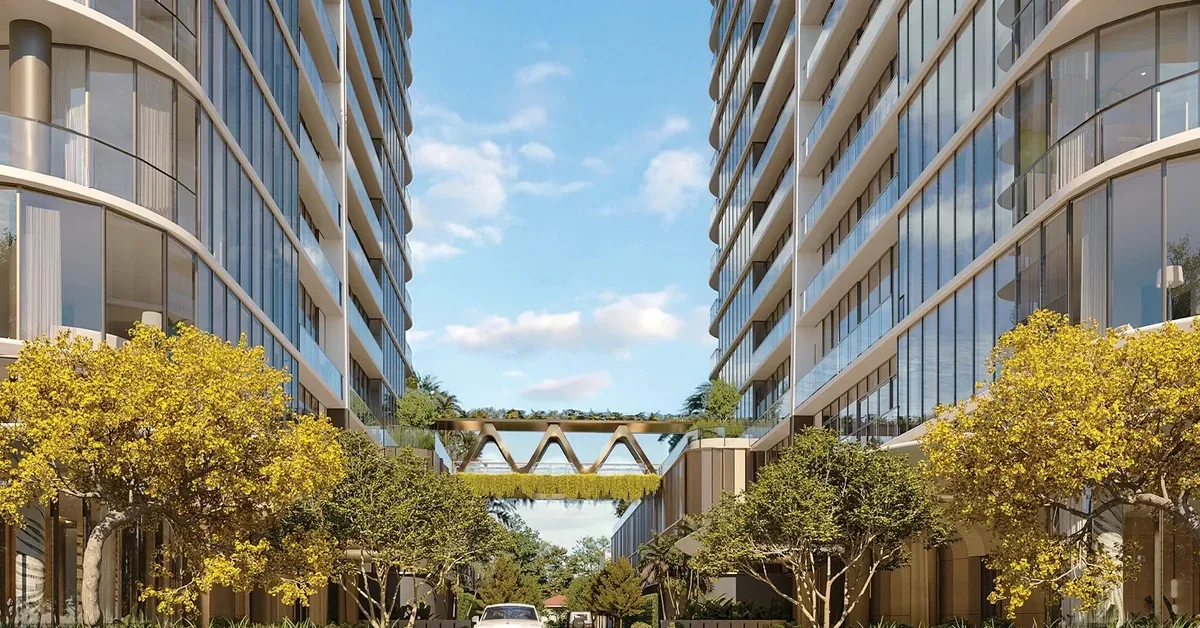
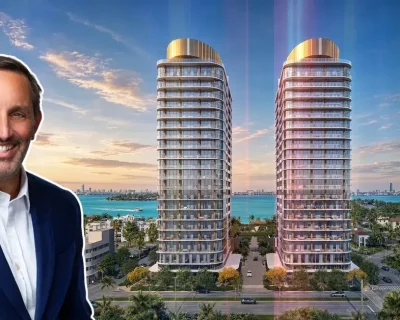
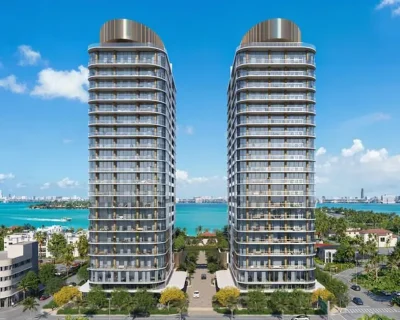
DaGrosa is also the founder and chairman of DaGrosa Capital Development Partners, a Miami-based real estate development firm focused on ground-up development and acquisitions of luxury hotels and residences. The firm is part of the team behind Kempinski Residences Miami Design District, Kempinski’s first stand-alone branded residential project in the United States. The condominiums are being developed by Biscayne Residences Holdings LLC, the project’s legal developer.
That connection gives DaGrosa’s comments an additional real estate development perspective. His view of buyer psychology, pricing and construction conditions is informed by work across investment, hospitality and residential development, including a major Miami project that brings together DaGrosa Capital Development Partners and Kempinski’s hospitality expertise.
The Rate Increase Changes the Negotiating Balance
Federal Reserve policymakers voted unanimously to lift the target range for the federal funds rate by 25 basis points, from 3.5%-3.75% to 3.75%-4%. FOX Business noted that this was the first increase since July 2023, after rates were left unchanged at the first five meetings of 2026.
Refinancing costs were already moving higher. According to figures cited from the Mortgage Research Center, the average 30-year fixed refinance rate rose to 7.14% from 6.87% one week earlier, while the average 15-year fixed refinance rate reached 6.30% on Thursday.
For sellers, those numbers reduce affordability even when asking prices do not change. DaGrosa said many homeowners have benefited from substantial appreciation over the past eight to 10 years, but some may need to accept a lower price to complete a sale. He also pointed to weak homebuilder sentiment and rising construction costs as added pressure on the supply side.
Mortgage Lock In Keeps Inventory Frozen
The market is also constrained by the mortgage-rate lock-in effect. Millions of owners hold loans below 4% and have little financial incentive to replace them with a more expensive mortgage. Rubin called those low rates ‘golden handcuffs’: comfortable owners may postpone a discretionary move, even as households relocating for work or responding to other life changes still need to buy or sell.
Rubin cautioned that a durable relationship between higher rates and lower home values would require consistent increases over an extended period. In the near term, however, hesitant buyers and longer listing periods are already encouraging more price reductions, according to his account.
Patient Buyers May Gain Leverage
DaGrosa expects bargaining power to move toward buyers as inventory lingers and seasonal activity slows. He described the immediate outlook as a frozen market, but said, “For the average American, my view is there are going to be good deals coming over time.”
Rubin likewise expects a slowdown, with the spring market likely to provide a clearer test of how fully the rate increase has changed buyer behavior and home values. Until then, sellers who need to move may have to compete through price, while buyers with time and financing flexibility can afford to be selective.
Read the full story at FOX Business.